The Illusion of Probabilities: How Cognitive Biases and Survivor Bias Distort Our View of Success and Career Choices

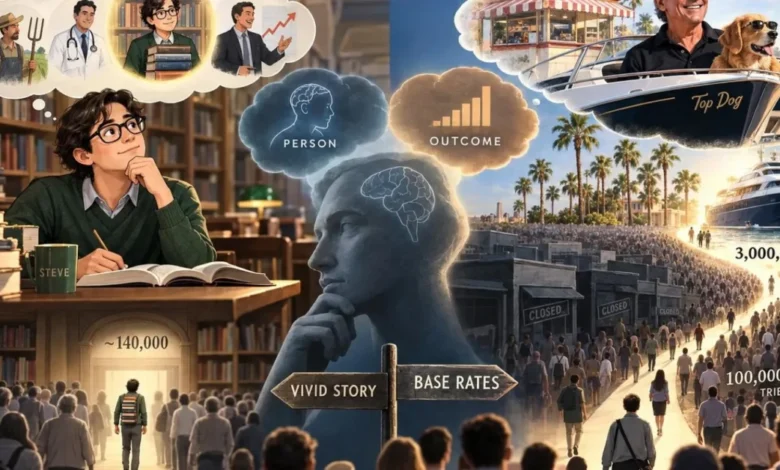
In modern cognitive psychology classrooms, educators frequently deploy a classic decision-making demonstration originally developed by behavioral pioneers Daniel Kahneman and Amos Tversky. Students are presented with a psychological sketch of an individual named Steve: he is described as very shy and withdrawn, invariably helpful yet showing minimal interest in people or the real world. He is portrayed as a meek, tidy soul with an acute need for order, structure, and a deep passion for detail. When asked to deduce Steve’s profession from a list including a physician, a farmer, a salesperson, and a librarian, the overwhelming majority of students instantly select "librarian."
This predictable cognitive leap relies on the representativeness heuristic—a mental shortcut where individuals evaluate the likelihood of an event by comparing it to an existing prototype in their minds. Because Steve fits the cultural stereotype of a quiet, bookish person, students overlook base-rate statistical probabilities. In reality, the mathematical bet should be placed on "salesperson." The United States hosts approximately 140,000 librarians, compared to more than 13 million individuals employed in sales roles. By focusing exclusively on diagnostic information—the vivid personal description—the students completely disregard the underlying population frequencies of these occupations.
This same fallacious reasoning, operating in reverse, permeates contemporary media narratives regarding personal wealth and entrepreneurship. Recently, popular news aggregators and financial publications have aggressively promoted profiles of "Everywhere Millionaires." Adapted from recent research by academic economists, these stories frequently highlight ordinary individuals who built modest, unglamorous businesses—such as HVAC contractors, veterinary practices, and local restaurant chains—into engines of immense prosperity. Yet, these articles often lean on outlier figures, such as Dick Portillo, who founded a Chicago-area hot dog stand, expanded it into a massive regional empire, sold it for a reported billion dollars, and subsequently retired to a 130-foot yacht named Top Dog docked in Naples, Florida.
The overarching message of such narratives is undeniably appealing: everyday citizens do not need to invent groundbreaking artificial intelligence software, commercialize autonomous vehicles, or build private rockets to achieve extraordinary financial success. Traditional, unglamorous Main Street businesses can quietly mint millionaires over decades of dedicated operation. However, this inspirational framing masks a profound structural flaw in probabilistic reasoning. Just as the classroom students incorrectly map Steve’s personality to a rare profession while ignoring base rates, readers of success memoirs look at the glittering endgame of a billion-dollar exit and fail to calculate the infinitesimal baseline probability that an ordinary hot dog stand will ultimately command a billionaire valuation.
Uncovering the Mechanics of Survivor Bias
To understand the mechanics driving these skewed perceptions, analysts must examine the pervasive influence of survivor bias—a logical error of concentrating on the entities that passed a selection process while completely ignoring those that did not, typically because of their public invisibility. In the context of American entrepreneurship, recent economic literature attempts to quantify the population of Everywhere Millionaires, estimating roughly three million individuals meeting specific wealth criteria within a total national population of approximately 340 million. This yields a prevalence rate of roughly 1 in 100 to 1 in 50 households.
Statistically speaking, these figures mean that ordinary millionaires are quietly integrated into everyday American life. They may sit a few rows behind a parent at a youth baseball game or coach a local soccer team. However, titans like Dick Portillo represent the extreme right tail of the statistical distribution—the absolute outliers of economic success. Media outlets preferentially feature these extreme anomalies because extraordinary wealth generates compelling human-interest stories, whereas routine business failures do not.
The structural reality of business creation underscores this statistical chasm. Filing the legal paperwork to establish a limited liability company (LLC) or a sole proprietorship is friction-free and accessible to nearly anyone. The true barrier lies in long-term survival. Historical economic data indicates that only about one-third of newly launched businesses survive past their first decade. Portillo’s hot dog enterprise endured and expanded across half a century, navigating sweeping economic recessions, shifting consumer dietary trends, intense commercial competition, and complex regulatory environments.
When researchers and journalists begin their investigations with a fully realized success story and trace backward chronologically, constructing a linear narrative of strategic decisions, grit, and market timing feels deceptively simple. Yet, this methodology commits a fundamental investigative error: it fails to account for the countless entrepreneurs who followed identical operational pathways, adopted similar business plans, and ultimately faced bankruptcy, forced liquidation, or meager earnings. Without analyzing the denominator—the vast population of failed enterprises—conclusions drawn from successful founders remain statistically invalid.
Evaluating Base Rates and the Illusion of Direct Pathways
To their credit, the economists who authored the underlying studies on Everywhere Millionaires are acutely aware of base rates. Their research demonstrates that a significant majority of successful business founders originate from lower-income or middle-class backgrounds. This demographic distribution occurs simply because the vast majority of the American population resides outside the top one percent of earners. In this specific regard, the researchers successfully avoid the "Steve the Librarian" trap by acknowledging the sheer volume of the broader demographic pool.
However, the analytical framework falters when tracing subsequent probabilities. While the literature correctly notes where founders started, it rarely begins with the entire cohort of aspiring entrepreneurs to calculate conversion rates. For instance, assertions that individuals from affluent backgrounds possess significantly higher statistical advantages in launching viable enterprises often lack the necessary baseline context to assess absolute risk.
Returning to the classroom cognitive experiment provides a clarifying lens. If an observer were to study exclusively professional librarians, they would undoubtedly discover a high concentration of introverted, orderly individuals who cherish books and value quiet environments. Observing this isolated sample might lead an uncritical analyst to conclude that possessing these personality traits is the definitive causal mechanism for becoming a librarian.
Yet, the thought experiment in reverse exposes the fallacy: the vast majority of quiet, orderly individuals are not librarians, just as the overwhelming majority of people who open neighborhood restaurants or hot dog stands will never command billion-dollar buyouts. Blending vivid individual narratives with systemic economic outcomes creates a dangerous illusion of predictability.
Broader Implications for Career and Financial Planning
The systemic misinterpretation of statistical probabilities carries profound implications for individual financial planning, career counseling, and public discourse. When major financial journalism frames outlier financial success as an accessible, repeatable blueprint for the average citizen, it encourages survivorship-biased decision-making.
Behavioral economists and financial advisors caution against making life-altering capital investments—such as draining retirement savings to fund high-risk hospitality or retail ventures—based on anecdotal media profiles. While entrepreneurship remains a vital engine of economic mobility and personal fulfillment, prospective business owners must evaluate ventures through a realistic lens of survival rates, operational costs, and market saturation rather than romanticized media portrayals.
Ultimately, the human brain remains hardwired to seek narrative coherence and personalized meaning, often at the expense of dry, unexciting statistical data. Whether students are misidentifying a librarian based on a personality sketch or aspiring entrepreneurs are projecting themselves onto the deck of a billionaire’s yacht after opening a local eatery, the root cognitive error remains identical. Recognizing the hidden baseline probabilities—and understanding the silent graveyard of unseen failures—remains the single most effective defense against the seductive narratives of modern media and flawed human intuition.
Related posts: